
In today’s robust mergers and acquisitions market, virtually every privately held company receives regular outreach from private equity groups, strategic acquirers, and business brokers indicating interest in acquiring the business. Sometimes one of those interested parties clicks with the owner, and conversations begin. In some cases, owners go so far as to provide financial statements or other sensitive information before fully understanding the implications.
If you find yourself in this situation, proceed carefully. An interested buyer can be a great opportunity, but how you handle the process from the beginning can have a significant impact on confidentiality, negotiating leverage, and ultimately the value and terms you receive.
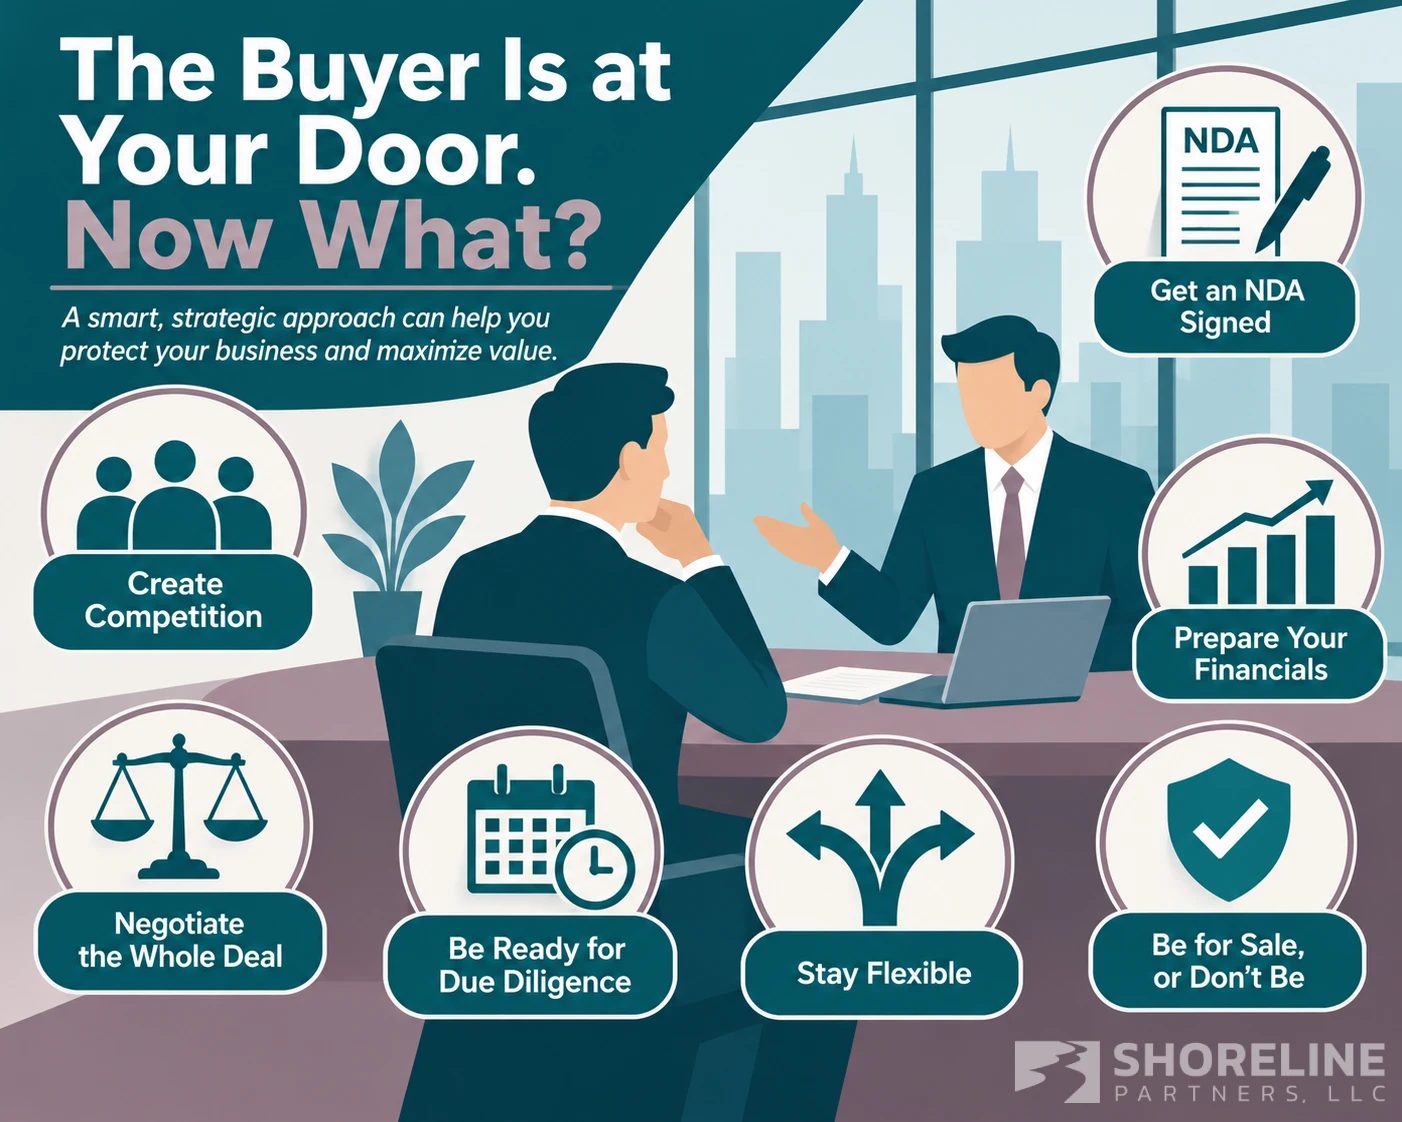
Put an NDA in Place Before Any Conversation
One of the most important rules in any potential transaction is simple: always have a non-disclosure agreement (NDA) executed before discussing your business with a prospective acquirer.
Many owners assume an informal discussion is harmless. It is not. Without a signed NDA, there is little protection around information shared during a phone call, meeting, or email exchange. Once you indicate that you may be willing to sell, you have effectively told that party your company is available. There may be nothing preventing them from sharing that information with an existing portfolio company, industry contacts, competitors, or others.
The consequences can be significant. Employees may hear rumors that the company is for sale. Customers may question your long-term plans. Competitors may use the uncertainty to their advantage. Even if a transaction never materializes, damage to the business can occur.
Before sharing any information with a potential acquirer, review our article on “The Importance of NDAs in M&A Transactions” to understand why confidentiality protections should be established from the outset.
Understand That Interest Does Not Equal Competition
Many business owners assume that because one buyer has expressed interest, they have all the leverage they need. In reality, competition is often the most effective way to maximize value.
In any transaction, the best way to determine what a business is worth is to create an environment where prospective buyers know they may not be the only party at the table. Buyers tend to be more aggressive when they believe they are competing for an opportunity.
We are frequently introduced to business owners who have already had conversations with one or more interested acquirers. Even when those discussions are underway, engaging an experienced M&A advisor can create an aura of competition. Interested parties often do not know whether discussions are limited to them or whether additional buyers may be evaluating the opportunity.
That perception alone can strengthen negotiating leverage and improve outcomes, even when a broad market process has not yet been launched.
Be Careful What Financial Information You Share
Another common mistake is providing historical financial statements directly to a prospective buyer without first preparing the information properly.
Many owners assume buyers will automatically recognize discretionary expenses, owner-specific costs, or other adjustments that should be added back when determining earnings. Often, that assumption proves incorrect. Instead, buyers frequently focus on the historical financial statements they receive and begin forming value expectations around those numbers. Once that anchor has been established, it can be difficult to redirect the conversation.
This is why properly adjusted or “recast” financial statements are so important. Adjusted EBITDA often provides a more accurate picture of what the business’s earning power under new ownership would look like than raw historical results alone. For a deeper discussion, see “What Financials Should I Present to Prospective Buyers?”
While it is possible to introduce recast financials later in the process, doing so can create challenges because the buyer may already be focused on the original financial information provided.
Negotiating a Deal Involves Much More Than Price
Many business owners focus primarily on value, but transaction value is only one component of a successful sale. Payment terms, working capital requirements, earnouts, seller financing, escrow provisions, indemnification obligations, and post-closing employment expectations can have a major impact on the ultimate outcome.
Experienced buyers negotiate transactions regularly. Most business owners sell a company only once. That experience gap matters.
Just as you would not perform your own dental work, we believe business owners should have experienced advisors representing their interests throughout the process. The structure of a transaction can dramatically affect both risk and proceeds.
Don’t Underestimate the Demands of Due Diligence
Even after reaching agreement with a buyer, the work is far from over. Due diligence is often one of the most time-intensive phases of a transaction. Buyers will request detailed information regarding financial performance, customers, employees, contracts, operations, legal matters, and more.
At the same time, the owner must continue running the company. This balance is critical. A decline in performance during due diligence can cause buyers to reduce their offer, delay closing, or attempt to renegotiate terms altogether. Maintaining business momentum while managing transaction demands requires planning and discipline.
Be Prepared to Pivot
Every prospective buyer conversation should begin with preparation and a clear strategy. Understanding the strategic motivations behind an acquisition often provides valuable negotiating insight.
Equally important, we are always prepared to pivot. If conversations with a single buyer don’t progress as expected, circumstances may warrant a broader outreach to additional qualified buyers. Having that capability provides meaningful leverage and helps ensure the owner retains options throughout negotiations.
Be for Sale, or Don’t Be for Sale
One of the biggest mistakes we see is treating a potential sale casually. Business owners should be deliberate. Either commit to evaluating a sale opportunity through a structured process or decide not to be for sale. It’s okay to tell an interested party on the phone that you’re not for sale but you’ll keep their information. The middle ground can create unnecessary risk.
Confidentiality can be compromised. Market rumors can spread. Employees, customers, and competitors may react in ways that harm the business. Whether you are speaking with one buyer or twenty, the same fundamental principles should apply.
A disciplined sale process protects confidentiality, enhances leverage, and positions owners to achieve the best possible outcome. Learn more about our sell-side services.
If you’ve been contacted by a prospective buyer and are considering your options, Shoreline Partners can help you evaluate the opportunity, protect confidentiality, and negotiate from a position of strength. Contact us to discuss your situation and determine the best path forward.